
NFIP VS PRIVATE FLOOD COMPAREComparing homeowners insurance in Texas requires more than checking annual premiums. To compare policies fairly, homeowners should match dwelling limits, deductibles, roof settlement provisions, liability coverage, water damage protection, and exclusions before looking at price.
Flood insurance requires a separate comparison because standard homeowners policies generally exclude flooding. Texas homeowners should evaluate both National Flood Insurance Program (NFIP) and private flood insurance options to understand their total protection.
Whether you live in Houston, Sugar Land, Richmond, Katy, or elsewhere in Texas, the right comparison can reveal meaningful differences between two seemingly similar quotes.
TL;DR
- Compare coverage before price. Two policies with different deductibles, limits, or exclusions are not equivalent.
- Check your wind and hail deductible. On a home insured for $400,000, a 2% deductible equals $8,000.
- Understand how your roof is insured. Replacement cost, actual cash value, and roof payment schedules can produce very different claim payments.
- Don’t assume flooding is covered. Standard homeowners policies usually exclude flood damage.
- Compare NFIP and private flood insurance. Their limits, exclusions, waiting periods, and available options can differ.
The bottom line: The cheapest policy is not necessarily the best value. The better policy is the one that provides appropriate protection at a competitive price.
1. Why Is the Cheapest Homeowners Insurance Quote Not Always the Best?
A cheaper homeowners insurance quote may have a higher deductible, lower coverage limit, narrower water damage protection, or less favorable roof settlement terms.
For example, two Texas homeowners policies might each provide $400,000 in dwelling coverage, yet one could have a 1% wind and hail deductible while the other has a 5% deductible.
That difference could mean paying $4,000 versus $20,000 toward a covered wind or hail loss.
The important question is not simply “Which policy costs less?” It’s “What protection am I giving up for the lower price?”
The Texas Department of Insurance recommends comparing coverage needs, deductibles, discounts, and company information before choosing a policy.
A better way to judge value
Consider three factors together:
- Protection: What losses are covered, and how much will the insurer pay?
- Financial exposure: How much might you need to pay after a claim?
- Premium: What is the annual cost of that protection?
A meaningful insurance comparison evaluates all three.
2. What Should You Compare on Every Texas Homeowners Insurance Policy?
The most important homeowners insurance comparison factors are dwelling coverage, personal property, liability, additional living expenses, deductibles, claim settlement methods, exclusions, and optional endorsements.
Use the following checklist before accepting a quote.
| Coverage item | Why it matters | What to compare |
|---|---|---|
| Dwelling coverage | Pays toward repairing or rebuilding the insured home | Replacement-cost estimate and dwelling limit |
| Other structures | Protects eligible detached structures | Coverage limits and exclusions |
| Personal property | Covers belongings after eligible losses | Limit, deductibles, and ACV vs. replacement cost |
| Personal liability | Helps protect against covered injury or property-damage liability | $300,000 vs. $500,000 or other available limits |
| Additional living expenses | Helps pay certain extra costs when a covered loss makes the home uninhabitable | Limit, duration, and exclusions |
| Wind and hail | Important for Texas storms | Coverage inclusion, exclusions, separate deductible |
| Roof settlement | Determines how eligible roof losses are calculated | Replacement cost, ACV, or payment schedule |
| Water damage | Covers certain types of water-related losses | Sudden pipe leaks, backup, seepage, and exclusions |
| Flood insurance | Covers qualifying flood damage under a separate policy | NFIP vs. private coverage |
| Endorsements | Modify or extend policy coverage | Sewer backup, foundation-related coverage, and other options |
Coverage varies by carrier, policy form, and endorsements.
Why dwelling coverage matters
Dwelling coverage should reflect the estimated cost to rebuild your home, not simply its market price or outstanding mortgage balance.
Land value does not represent rebuilding expenses, and construction costs can change over time.
Ask whether the insurer has updated its replacement-cost estimate for your property’s square footage, materials, design, and local labor costs.
Why roof settlement matters
A home insurance policy may settle covered roof losses using replacement cost, actual cash value, or a roof payment schedule.
These differences can substantially affect what a homeowner receives after hail or wind damage.
Always request the relevant policy wording, not just the quote summary.
Infographic placement #1: What to Compare on a Texas Home Insurance Quote
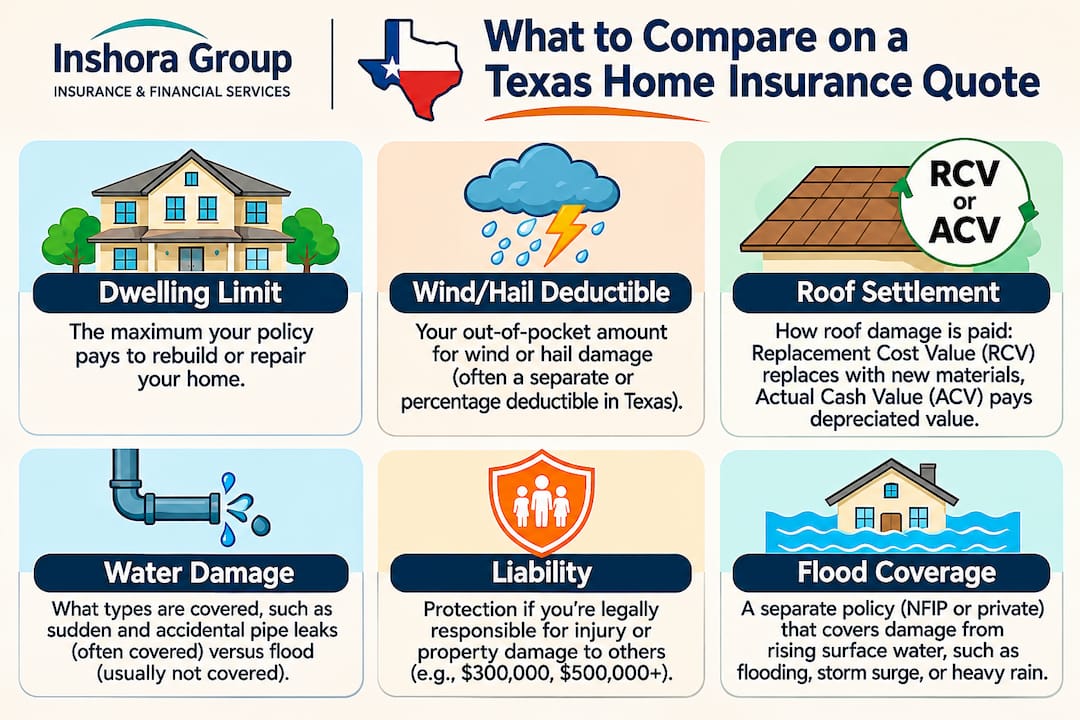
Source: TDI Home Insurance Shopping Guide
3. How Do 1%, 2%, and 5% Wind and Hail Deductibles Work in Texas?
A percentage deductible is generally calculated using the insured dwelling amount specified in the policy, rather than the home’s market value.
This distinction is important because percentage-based wind and hail deductibles can produce large out-of-pocket costs.
Example: A Texas home insured for $400,000
| Wind/hail deductible | Calculation | Deductible amount |
|---|---|---|
| 1% | $400,000 × 1% | $4,000 |
| 2% | $400,000 × 2% | $8,000 |
| 5% | $400,000 × 5% | $20,000 |
These are educational calculations, not insurance premium estimates.
What happens after a $25,000 covered hail claim?
For this simplified example, assume the repair cost is fully covered and no other exclusions, limits, depreciation, or special settlement conditions apply.
| Deductible | Homeowner pays | Insurer pays |
|---|---|---|
| 1% | $4,000 | $21,000 |
| 2% | $8,000 | $17,000 |
| 5% | $20,000 | $5,000 |
A 5% deductible can dramatically reduce claim payments compared with a 1% deductible.
However, a higher deductible may also lower your annual premium.
Which deductible should you choose?
The decision depends on:
- Your emergency savings
- Annual premium savings
- Your tolerance for large out-of-pocket costs
- Your home’s storm exposure
- The coverage and deductible options offered by each carrier
Compare the annual savings against the additional amount you would need to pay after a claim.
A lower premium isn’t valuable if the deductible would create a financial burden you cannot reasonably handle.
Infographic placement #2: 1% vs. 2% vs. 5% Wind/Hail Deductibles

Source: TDI — What to Know About Deductibles
4. Replacement Cost vs. Actual Cash Value: What’s the Difference?
Replacement cost value (RCV) generally reflects the covered cost to repair or replace damaged property at current prices, subject to policy conditions and limits.
Actual cash value (ACV) accounts for depreciation, potentially reducing the claim payment.
The difference is particularly important when comparing policies covering roofs and personal belongings.
Example: A damaged Texas roof
Assume:
- Covered roof replacement cost: $20,000
- Depreciation for this example: $8,000
- Applicable deductible: $4,000
| Claim calculation | Replacement cost | Actual cash value |
|---|---|---|
| Covered replacement cost | $20,000 | $20,000 |
| Depreciation | Potentially recoverable | $8,000 deducted |
| Deductible | $4,000 | $4,000 |
| Potential total insurer payment | $16,000 | $8,000 |
Under an RCV policy, the insurer may initially withhold depreciation until repairs or replacement are completed and documented.
Under an ACV settlement, depreciation generally is not recoverable.
These examples exclude other provisions and assume the stated depreciation and damage figures are applicable.
What about roof payment schedules?
Some policies use age-based or material-based roof schedules. These can affect payment even when another part of the policy uses replacement-cost terms.
Ask your agent:
“If hail damages my roof tomorrow, exactly how will the insurer calculate what it owes?”
That question is more useful than simply asking whether the policy has roof coverage.
Source: Texas OPIC — ACV vs. RCV
5. What’s the Difference Between Homeowners Insurance and Flood Insurance?
Homeowners insurance and flood insurance protect against different causes of damage.
Standard homeowners policies commonly cover certain fire, theft, wind, and sudden accidental water losses, subject to exclusions and conditions.
Flood insurance is designed for qualifying flooding, such as certain events involving rising surface water, overflowing rivers, or storm surge.
A standard homeowners policy generally does not cover flood damage.
Homeowners insurance vs. flood insurance
| Damage or coverage | Homeowners insurance | Separate flood insurance |
|---|---|---|
| House fire | Commonly covered | Not a flood coverage |
| Theft | Commonly covered | Not a flood coverage |
| Wind damage | Often covered, but may be excluded | Not generally covered as a wind loss |
| Sudden burst pipe | Often covered, subject to conditions | Not ordinarily covered unless tied to qualifying flooding |
| Rising surface water | Usually excluded | Potentially covered |
| River or bayou overflow | Usually excluded | Potentially covered |
| Storm surge | Generally excluded as flood | Potentially covered |
| Personal belongings | Covered under applicable policy terms | Available with eligible contents coverage |
| Temporary housing | May be covered after an eligible homeowners loss | Not covered by standard NFIP policies |
Coverage depends on the specific policy and cause of damage. Some private flood policies provide additional benefits not available through the NFIP.
Why this matters around Houston
A heavy rainstorm can create several kinds of losses.
Water entering through a storm-damaged roof and water rising from the street into your home may be treated differently by insurers.
Even when damage happens during the same storm, the covered cause of loss determines which policy may respond.
Insert the homeowners-versus-flood infographic here.
Sources:
6. NFIP vs. Private Flood Insurance: Which Is Better for Texas Homeowners?
Texas homeowners can often consider two categories of flood insurance: coverage through FEMA’s National Flood Insurance Program (NFIP) and policies offered by private insurers.
Neither is automatically better for every property.
Your home’s replacement cost, flood exposure, coverage requirements, and the availability of private options all affect the decision.
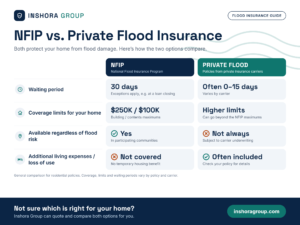 NFIP vs. private flood insurance comparison
| Feature | NFIP | Private flood insurance |
|---|---|---|
| Provider | Federal program administered by FEMA | Private insurance companies |
| Building coverage | Up to $250,000 for a single-family home | Varies by insurer; higher limits may be available |
| Contents coverage | Up to $100,000 for residential coverage | Varies by insurer |
| Waiting period | Generally 30 days, with exceptions | Varies by insurer and policy |
| Additional living expenses | Not covered | May be available |
| Coverage structure | Standardized federal policy forms | Terms and options vary |
| Availability | Subject to program eligibility and community participation | Subject to underwriting and insurer eligibility |
| Basement coverage | Subject to specific limitations | Varies by insurer |
| Best use | Homeowners who meet NFIP needs and eligibility | Homeowners seeking alternative limits or benefits, where available |
The important NFIP coverage limits
For a typical single-family home, the NFIP generally offers maximum coverage of:
- $250,000 for the residential building
- $100,000 for personal belongings
Building and contents coverage are separate.
Personal belongings are generally settled on an actual-cash-value basis under the NFIP.
If rebuilding your home would cost substantially more than $250,000, the NFIP limit alone may not replace your entire structure after a covered total loss.
You may want to investigate private flood coverage or excess flood coverage, depending on eligibility and availability.
Does NFIP flood insurance have a waiting period?
New NFIP policies generally take effect 30 days after purchase.
However, FEMA identifies exceptions, including certain mortgage-related transactions, specific policy renewals or changes, and certain flood-map or wildfire-related situations.
Do not assume a new policy becomes effective immediately.
Private insurers may offer different waiting periods, but terms must be verified before purchase.
What about temporary housing?
The standard NFIP policy does not cover additional living expenses while your home is being repaired after a flood.
Certain private flood policies may offer this benefit.
For some Texas homeowners, this difference is a major consideration when comparing policies.
Infographic placement #4: NFIP vs. Private Flood Insurance
Insert the NFIP comparison infographic here.
Sources:

7. Do You Need Flood Insurance Outside a High-Risk Flood Zone?
A property can experience flooding even if it is located outside a FEMA-designated high-risk flood zone.
Flood maps describe mapped risk, but they cannot guarantee a home will never flood.
Heavy rainfall, drainage limitations, nearby development, and overflowing waterways can create flooding in areas not classified as high-risk.
What does FEMA’s historical data show?
According to FEMA’s 2025 NFIP materials, almost one-third of NFIP claims from 2014 through 2024 came from areas outside mapped high-risk flood zones.
That statistic describes historical NFIP claims, not the percentage chance that any individual property will flood.
How can Texas homeowners check their flood zone?
UFEMA Flood Map Service Center.se the official
Enter your property address to view the available flood map information.
You should also consider:
- Previous flooding at the property
- Neighborhood drainage
- Nearby bayous, creeks, and waterways
- Local development and drainage changes
- Your lender’s flood insurance requirements
What if your lender doesn’t require flood insurance?
You can still consider purchasing it.
A mortgage lender’s requirement is not the same as a complete assessment of your financial risk.
For Houston-area homeowners, the decision deserves attention even when flood insurance is optional.
Sources:
8. How Much Does Homeowners Insurance Cost in Texas?
Texas homeowners insurance premiums vary considerably by property and carrier.
Factors may include:
- Location and storm exposure
- Rebuilding cost
- Roof age, materials, and condition
- Dwelling coverage amount
- Deductibles
- Claims history
- Available discounts
- Coverage options
- Carrier underwriting and pricing
What does Texas’s official insurance data show?
The Texas Department of Insurance’s 2026 market overview reports an average annual homeowners insurance premium of approximately $3,489 in its market snapshot.
This is a statewide historical average, not a quote for your home, and it should not be used to predict what a specific homeowner will pay.
Actual premiums in Sugar Land, Katy, Richmond, and Houston may be higher or lower.
You can explore sample prices and company information through HelpInsure.com, a resource supported by Texas insurance regulators.
To find your actual price, request comparable quotes using the same property information, coverage limits, and deductibles.
Source: TDI Texas Homeowners Insurance Market Overview
9. How to Compare Homeowners and Flood Insurance Quotes Fairly in Five Steps
The most effective insurance comparison is one that makes differences visible before you choose a policy.
Step 1: Establish your coverage baseline
Determine the dwelling replacement-cost estimate, desired liability limits, and coverage features you want.
Decide which optional protections are important, including water backup, roof settlement provisions, and separate flood insurance.
Step 2: Use consistent property information
Ask each insurer to quote the same property details, including:
- Property address
- Year built
- Roof age and material
- Square footage
- Construction details
- Desired dwelling limit
- Claims information
- Deductible preferences
Different inputs can distort your comparison.
Step 3: Build a side-by-side comparison
Create a comparison grid for each carrier.
| Feature | Quote A | Quote B | Quote C |
|---|---|---|---|
| Dwelling coverage | Verify | Verify | Verify |
| Liability limit | Verify | Verify | Verify |
| Wind/hail deductible | Verify | Verify | Verify |
| Roof settlement | Verify | Verify | Verify |
| Water damage provisions | Verify | Verify | Verify |
| Flood policy available | Verify | Verify | Verify |
| Endorsements | Verify | Verify | Verify |
| Annual premium | Compare last | Compare last | Compare last |
Do not assume three policies with similar premiums provide equivalent coverage.
Step 4: Review exclusions and claim payments
Look closely at:
- Percentage deductibles
- Roof depreciation or schedules
- Water damage limitations
- Flood exclusions
- Wind or hail exclusions
- Additional living expenses
- Conditions for receiving replacement-cost payments
Ask for clarification on anything that materially affects claim payments.
Step 5: Compare the total cost and value
Once coverage differences are understood, compare the annual premiums.
Consider whether the savings justify any higher deductible or narrower coverage.
The goal is to choose a policy that balances meaningful protection, affordability, and your willingness to assume financial risk.
10. How Inshora Group Helps Texas Homeowners Compare Insurance
Inshora Group is an independent insurance agency serving homeowners in Sugar Land, Richmond, Katy, Houston, and other Texas communities.
Rather than comparing only one insurance company’s offerings, our goal is to help homeowners review available carrier options and understand how each policy differs.
A meaningful comparison should cover:
- Annual premium
- Dwelling and personal property limits
- Wind and hail deductibles
- Roof settlement provisions
- Water damage coverage
- Flood insurance options
- Important exclusions and endorsements
Get Help Comparing Your Coverage
Insurance decisions should be based on more than the lowest quoted price.
If you’re purchasing a home, approaching renewal, or concerned about flood exposure, Inshora Group can help you review available options and identify questions worth asking before you purchase coverage.
Compare Texas Homeowners Insurance Options
Call: (713) 943-9985
Quotes, eligibility, availability, limits, and coverage depend on individual underwriting and policy terms.
Frequently Asked Questions
How do I compare homeowners insurance quotes fairly?
Start by matching dwelling coverage, liability limits, personal property coverage, and deductibles across the quotes. Then examine roof settlement, water damage provisions, endorsements, and exclusions. Once those differences are understood, compare premiums. An independent insurance agent can help explain the variations, but always review the actual policy documents before purchasing.
Does homeowners insurance cover flooding in Texas?
Standard homeowners insurance generally does not cover flooding from rising surface water, overflowing waterways, or storm surge. A separate flood insurance policy may cover qualifying losses. Homeowners should compare NFIP and private flood insurance options rather than assuming their standard homeowners policy protects them from every type of storm-related water damage.
What is the difference between NFIP and private flood insurance?
NFIP flood insurance is provided through a federal program with standardized coverage provisions and limits. Private flood insurance is offered by private insurers, with policy terms, limits, waiting periods, and optional benefits that vary. A homeowner should compare actual coverage documents, not just premiums, and confirm whether the policy meets applicable lender requirements.
Is a 2% wind and hail deductible high in Texas?
A 2% deductible equals $8,000 on a dwelling insured for $400,000. Whether that amount is appropriate depends on your savings, budget, storm exposure, and available coverage options. Compare the annual premium savings against the additional out-of-pocket cost you could face after a covered wind or hail claim.
Should I choose replacement cost or actual cash value coverage?
Replacement-cost coverage can provide stronger protection against depreciation, subject to the policy’s conditions and limits. Actual cash value deducts depreciation, which may leave you paying more after a loss. Homeowners should compare how roofs, personal property, and other covered items are settled because different parts of one policy may use different valuation methods.
Do I need flood insurance if my property is outside a high-risk flood zone?
Flood insurance may still be worthwhile. Properties outside mapped high-risk zones can flood from heavy rain, overwhelmed drainage systems, or overflowing waterways. Review FEMA flood maps, consider local flood history, and compare available policies. A lender’s decision not to require flood insurance does not mean the property has no flood exposure.
Can I switch homeowners insurance companies before renewal?
You can generally change homeowners insurance companies before your existing policy renews. Before canceling, make sure the replacement coverage is confirmed and effective, and coordinate with your mortgage lender if insurance is paid through escrow. Also review any refund, cancellation, or underwriting conditions that may affect the transition.
Is bundling insurance always cheaper?
Not necessarily. A carrier may offer a discount for purchasing multiple policies, but the bundled total is not automatically the lowest price or best overall protection. Compare the combined bundle against separate insurance options, keeping coverage and deductibles as consistent as possible. Review each policy independently before deciding.
Government Sources and References
The following resources provide official consumer guidance and insurance information:
- Texas Department of Insurance — Home Insurance Shopping Guide
https://www.tdi.texas.gov/consumer/home-insurance-shopping-guide.html - Texas Office of Public Insurance Counsel — Residential Property Shopping Guide
https://www.opic.texas.gov/residential-property-insurance/shopping-guide/ - Texas Department of Insurance — Deductibles
https://www.tdi.texas.gov/tips/deductibles.html - Texas OPIC — Actual Cash Value vs. Replacement Cost
https://www.opic.texas.gov/residential-property-insurance/basics/acv-vs-rcv/ - FEMA — National Flood Insurance Program
https://www.floodsmart.gov/ - NFIP — Types of Flood Coverage
https://agents.floodsmart.gov/topics/selling-flood-insurance/coverage - FEMA — Flood Map Service Center
https://msc.fema.gov/portal/home - TDI — Texas Homeowners Insurance Market Overview
https://www.tdi.texas.gov/general/texas-homeowners-insurance-market-overview.html - Texas Insurance Comparison Resource — HelpInsure
https://www.helpinsure.com/
Final Thoughts: Compare Coverage First, Price Second
Texas homeowners face important insurance decisions involving rebuilding costs, wind and hail deductibles, roof coverage, and flooding.
A policy that appears affordable today could leave you responsible for significant expenses after a covered loss.
By comparing consistent limits, deductibles, exclusions, and claim settlement terms, you can make a more informed decision.
Need help comparing homeowners and flood insurance in Texas?
Contact Inshora Group to discuss available coverage options and request a personalized comparison.
Inshora Group — Insurance & Financial Services
Sugar Land, Texas
https://www.inshoragroup.com/
(713) 943-9985
Educational information only. Coverage descriptions are general. All insurance protection is subject to the specific policy language, limits, deductibles, exclusions, eligibility, and applicable law.
