
Rated 4.9★ on Google from 350+ reviews · Independent insurance agency serving Houston and suburbs since 2013
Inshora Group is a local Fort Bend County agency with same-day quotes on home insurance in Fulshear, TX. We compare several carriers for your address, including new homes in ZIP 77441, and check the deductibles, roof terms and flood options before you buy.
Carriers we can quote for Fulshear homes
We help homeowners across Fulshear and the rest of Fort Bend County, including Cross Creek Ranch, Jordan Ranch, Fulshear Lakes and Polo Ranch. Tamarron sits in Fulshear’s extraterritorial jurisdiction (ETJ), so the mailing city may say Katy or Fulshear. City limits are checked per address.
Fulshear is one of the fastest-growing cities in the country. The U.S. Census Bureau estimates 64,630 residents on July 1, 2025, up 21.0% in a single year, the second-fastest growth rate among U.S. cities of 20,000 or more (Census CB26-80). Most of that growth is new construction, which is why so many of the homes we quote here are only a few years old.
Send us a renewal offer or a closing date. If you are buying a new build, or moving from Katy, Richmond or Sugar Land, we can shop coverage before closing. We also serve Missouri City. For what a Texas policy covers, see our home insurance guide.
For a 2025-built Fulshear home with about $600,000 in dwelling coverage, our recent quotes for homeowners insurance in Fulshear, TX have generally landed around $1,500 to $2,500 a year. That is roughly $125 to $210 a month. That is Inshora’s recent quoting experience, not an official city average. Your price depends on the roof, deductibles, wind and hail terms, claims history and credit-based insurance score. Flood insurance is a separate policy and is not included.
In our recent quotes, 2025-built Fulshear homes have generally come in below the 2025 Fort Bend County average of $4,231 for policies with wind coverage. That county average mixes home ages and sizes; it is context, not a savings promise.
No official average is published for Fulshear alone, so the county and state figures are context, not a quote for your house.
Usually several things at once: the company’s filed rate, a higher dwelling (rebuild) amount, an older roof, a new claim or a lost discount. Your company should be able to tell you what changed.
Statewide filings have eased: on October 8, 2026, TDI said most insurers filing since July 1 proposed decreases, averaging −4.3% over 90 days. That is a filed-rate average across companies, not a cut on every Fulshear bill.
Before you renew:
Send us your renewal and we will shop it the same day.
Want the number for your house? Send your address or renewal and we will quote it the same day.
A new build needs its own homeowners policy in force on the closing date. The builder’s warranty and the builder’s risk coverage carried during construction end or stay with the builder; neither one insures your house or belongings after you move in.
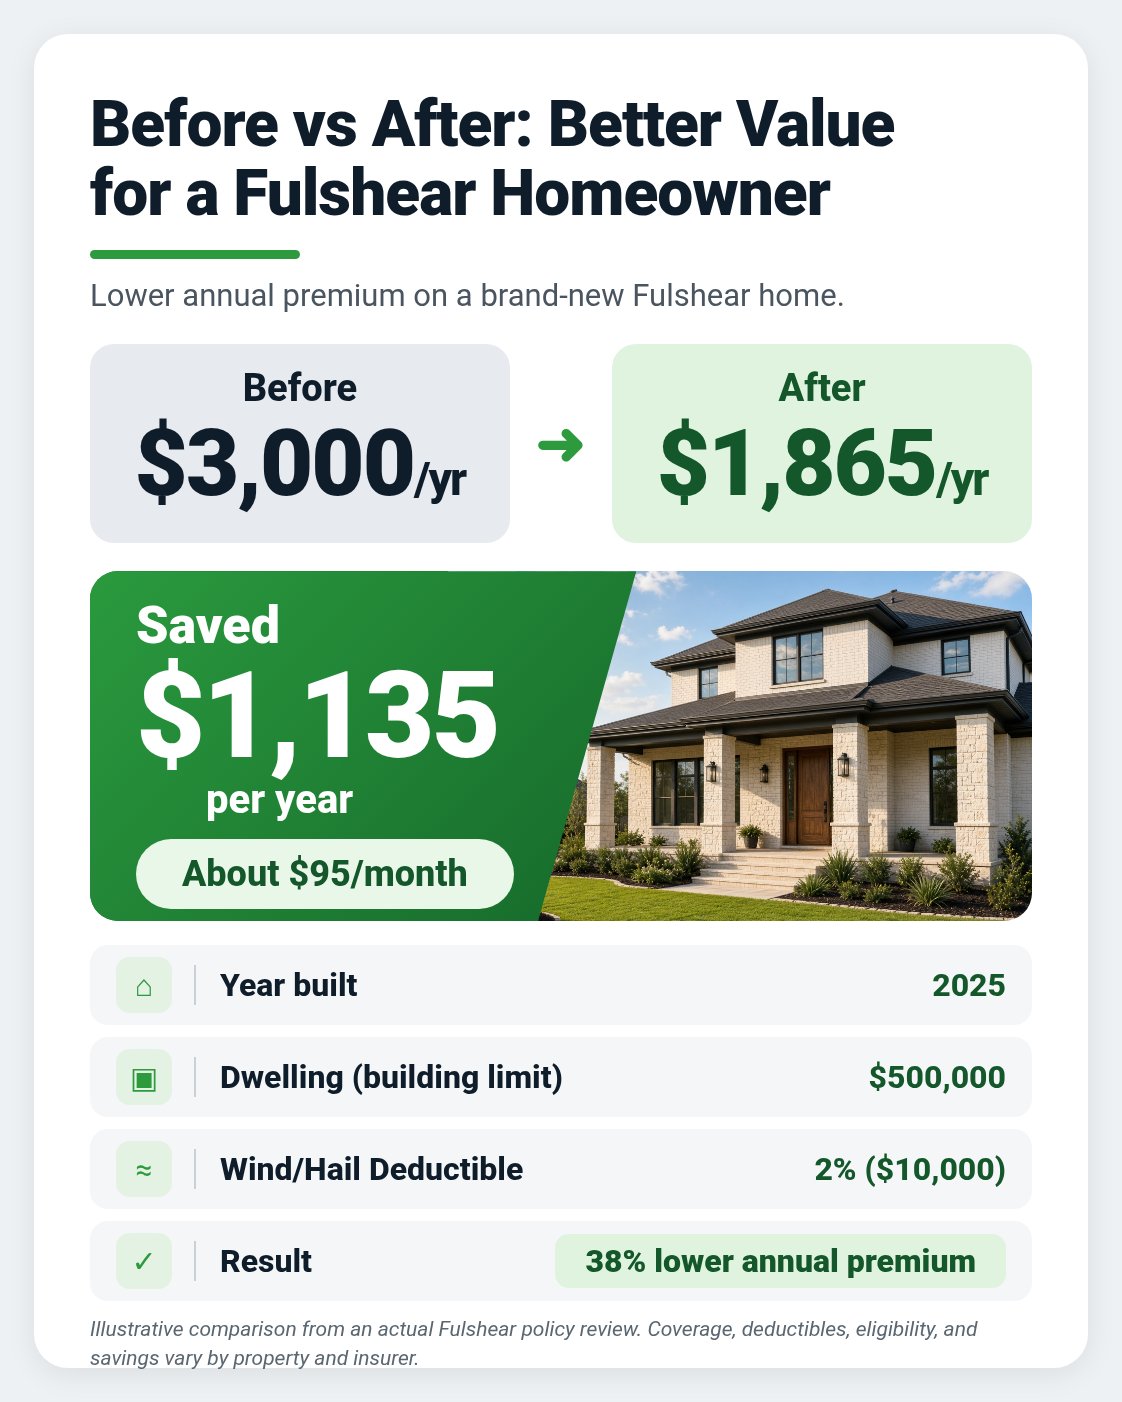
A percentage deductible is figured from your dwelling limit, not the repair bill. At a $500,000 dwelling limit, a 2% wind/hail deductible is $10,000 out of pocket. Enter your own dwelling amount:
Fulshear is not one flood zone. FEMA maps zones lot by lot, so neighboring houses can differ. A standard homeowners policy generally does not cover flood, including overflow from the Brazos River or Bessies Creek. Flood needs a separate policy: a National Flood Insurance Program (NFIP) policy or a private flood policy. Check the flood zone for the exact building in the FEMA Flood Map Service Center, not the neighborhood name or ZIP 77441.
If the building is in a high-risk zone (A or V) and the mortgage is federally backed, the lender must require flood insurance. Outside those zones it is optional, but FEMA reports that nearly one-third of NFIP claims from 2014 to 2024 came from outside high-risk areas (FloodSmart). During Hurricane Harvey in 2017, the Brazos reached major flood stage in Fort Bend County.
| Compare | Homeowners | NFIP flood | Private flood |
|---|---|---|---|
| Flood | Generally excluded | Covered as federally defined | Covered as the insurer defines it |
| Limits | Set by your policy | Up to $250,000 building, $100,000 contents | Varies; higher limits may be available |
| Start date | Per policy | Usually a 30-day wait | Varies by company |
Not sure about your deductible or flood zone? We will check both on your same-day quote, and add flood insurance if you want it.
For a 2025-built Fulshear home with about $600,000 in dwelling coverage, our recent quotes have generally landed around $1,500 to $2,500 a year. No official Fulshear average exists. Your price depends on the roof, deductibles, wind and hail terms, claims history and credit-based insurance score. Flood is extra. Get a same-day quote.
TDI reports a 2025 Texas average of $3,489 a year (preliminary). A compilation of TDI records by Texas Insurance Tracker puts the 2025 Fort Bend County average at $4,231 for policies with wind coverage. Neither figure includes flood or prices your specific house. See our home insurance guide.
Only in some cases. If the building is in a FEMA high-risk flood zone (zones starting with A or V) and the mortgage is federally backed, the lender must require flood insurance. Outside those zones it is usually optional, though a lender can still ask for it. Ask us about flood insurance.
It is still worth asking. Outside A or V zones, flood insurance is usually optional, but FEMA reports that nearly one-third of NFIP claims from 2014 to 2024 came from outside high-risk areas. Review your Fulshear address, nearby drainage and the cost of a separate policy. We can quote flood insurance with your home.
No. A standard homeowners policy generally excludes flood, including overflow from the Brazos River, Bessies Creek or rising surface water. That holds in Cross Creek Ranch and every other 77441 neighborhood. To cover flood damage you need a separate NFIP or private policy. Compare options on our flood insurance page.
Enter the street address in the FEMA Flood Map Service Center. Do not rely on the subdivision name, ZIP 77441 or a neighbor’s zone, because zones are set lot by lot. The City of Fulshear’s Check My Address tool tells you whether a house is inside city limits. We can run the lookup with your quote.
Parts of the area did. In 2017, Harvey pushed the Brazos River to major flood stage in Fort Bend County, and USGS inundation maps include Bessies Creek where it meets the Brazos near Fulshear. Past flooding nearby does not set the zone for your lot, so check the address. Learn more about flood coverage.
Usually not. Fort Bend County is outside TWIA, the Texas coastal wind pool, so wind and hail are normally included in the homeowners policy, often with a separate percentage deductible. At $500,000 of dwelling coverage, a 2% deductible is $10,000. Ask whether roof claims pay replacement cost. Read our home insurance guide.
There is no single best company for every Fulshear house. The right fit depends on your roof, rebuild cost, deductibles and budget. As an independent Fort Bend County agency, we shop several carriers for 77441 addresses, including Allstate, Hartford, Progressive and Liberty Mutual, and compare price, deductibles and coverage side by side. Contact our team.
Yes. Most carriers let you put home and auto on one account, and a multi-policy discount may lower one or both premiums. A bundle is not automatically the cheapest choice, so compare the combined annual cost and coverage against separate policies. We can quote auto insurance with your home.
A new build in Cross Creek Ranch, Jordan Ranch, Fulshear Lakes or Polo Ranch needs its own homeowners policy at closing. A builder warranty or HOA coverage does not replace it. Start with a rebuild estimate, a wind and hail deductible in dollars and a flood-zone lookup for the lot. Moving from Katy? Shop before closing.
Start by shopping, which TDI recommends doing regularly. Then ask about discounts such as bundling home and auto, pick a wind/hail deductible you can afford in dollars, and make sure your roof age and square footage are listed correctly. A newer roof also helps. We compare several carriers for 77441 addresses. Get a same-day quote.
Usually, but it may pay less. As a roof ages, some companies switch it from replacement cost to actual cash value (ACV), which subtracts depreciation. In TDI’s example, a 10-year-old roof that costs $10,000 to replace has an ACV of about $7,000 before the deductible. A roof in poor condition can be excluded. See our home insurance guide.
Start shopping right away. Texas companies must give 60 days’ notice of a nonrenewal for policies bought or renewed since 2024, and for nonrenewals after January 1, 2026, a written reason. Your coverage lasts until the end date. If two companies turn you down, the Texas FAIR Plan is the backup. Send us your nonrenewal notice and we will shop it the same day.
Same-day quotes for Fulshear homeowners. Send your renewal or declarations page, or the address and closing date for a new home.
Explore auto, renters, rental property, life and business insurance. Standard renters insurance generally excludes flood damage; ask about separate flood contents protection.
Updated November 2026. Coverage descriptions are general; prices, eligibility and terms depend on the insurer and policy.

© 2026 Inshora Group. All Rights Reserved.