
Homeowners insurance · Cypress, TX
Rated 4.9 on Google from 350+ reviews
Is Cypress, TX in a flood zone? Some lots are, and some aren't — it depends on your address, not the ZIP.
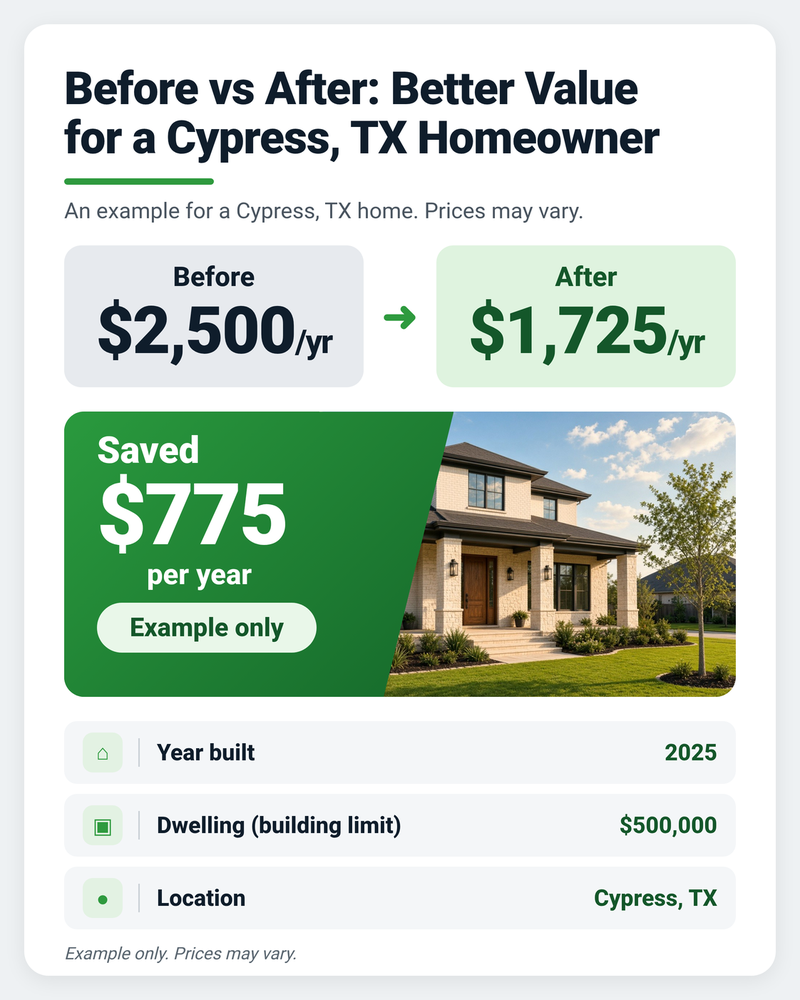
Compare 25+ insurance companies for your Cypress home, usually the same day.
Inshora Group is a local, independent Fort Bend County agency serving Houston and its suburbs since 2013.
Renewal went up? · Buying or building in Cypress? · Is Cypress in a flood zone?
We help homeowners across Cypress, including Bridgeland, Towne Lake and other Cypress communities in ZIP codes 77429 and 77433.
We work with 25+ insurance companies. Here are some of the companies we compare:


A few Google reviews, quoted from Google (some are shortened). Read all 350+ reviews on Google.
Inshora has been absolutely amazing! I went to them looking for home owners insurance at first, and they beat my farmers quote by over 1k per year.
Inshora Group is amazing! Great customer service, personalized service and they saved me more than $600 a year for better car insurance coverage–phenominal!
Cypress is an unincorporated community in northwestern Harris County, on U.S. Highway 290 twenty miles northwest of Houston (Texas State Historical Association). There is no City of Cypress, so Harris County handles floodplain questions. The name covers a wide stretch of neighborhoods, not a single city-limit line. Neighboring Tomball is different: it is an incorporated city to the north, with its own city hall and floodplain office. We keep the two communities on separate pages because the questions, the maps and the housing stock are not the same.
Because Cypress isn't an incorporated city, the Census Bureau doesn't publish a "Cypress city" population. The closest official snapshot is the two main ZIP Code Tabulation Areas. The ACS 2020-2024 5-year estimates put 96,334 people in 77429 and 116,550 in 77433 (Census Reporter, 77429; Census Reporter, 77433). Those ZIPs together describe a lot of the Cypress mailing area, but they are not a city count, and a few Cypress addresses sit outside them.
We help homeowners in Cypress communities such as:
Bridgeland and Towne Lake are large, newer master-planned communities, but they are not all of Cypress. Many houses in 77429 are older, and the roof and rebuild cost on those streets can look very different from a new house in 77433. People also say Cy-Fair for this part of northwest Harris County. The Cypress-Fairbanks Independent School District grew out of the first Cypress school, which opened in 1884 (TSHA). That name is a useful way to describe the area; it does not, by itself, set a homeowners rate. We still quote the street address.
Mailing ZIP is a starting point, not the rate. We price the lot: how much it would cost to rebuild, what the roof looks like, and where it sits on the flood map. If you're moving from Tomball, Katy, Houston, Sugar Land, Missouri City, Richmond or Fulshear, we can line up coverage before closing day. Our home insurance guide walks through the basics.
The premium follows the house on that lot, not the Cypress name on the mailbox. Rebuild cost, the roof's age and condition, the wind and hail deductible you pick, and any claims on the file usually move the number more than the community name. A newer Bridgeland house and an older home in 77429 can come back with very different quotes. Send us the address and we'll shop it, usually the same day.
What a house might sell for and what it would cost to rebuild are not the same number. The Census Bureau's ACS 2020-2024 5-year estimates, table B25077 (median value of owner-occupied homes), put that median at $369,000 in 77429 (±$10,427) and $409,400 in 77433 (±$16,794) (Census Reporter, 77429; Census Reporter, 77433). They are five-year averages of what owners think a house would sell for, which is not the same as rebuilding it. We shop the rebuild cost, because that is the figure TDI says companies lean on when they price a policy.
There's no single Cypress premium we can post, because two houses on the same street can price out differently. Here's the latest from TDI, the state regulator. On October 8, 2026, TDI said most homeowners insurers that filed rate changes since July 1, 2026 proposed decreases, affecting about 700,000 Texas policyholders. Filed homeowners rate changes over the 90 days before that Oct. 8, 2026 release averaged a 4.3% decrease (TDI). That's a statewide average, not your renewal. Those figures are not a quote for 77429 or 77433. If yours still went up, send it to us and we'll shop it.
Curious what your Cypress house would quote today? Email the declarations page, or just the street address, and we'll start the same day.
In Cypress, flood risk is an address question. Cypress Creek and Little Cypress Creek run through this part of northwest Harris County, and lots near those channels can sit in a mapped high-risk zone while a house a few streets over does not. Cypress has no city floodplain office, so for an unincorporated Harris County address you can check the FEMA Flood Map Service Center and the Harris County Flood Education Mapping Tool, and follow up with the Harris County Permits office if you need a floodplain determination or an elevation certificate.
Harris County's draft updated maps (MAAPnext) are informational only and don't replace the current FEMA effective map for insurance or permitting.
Harvey in August 2017 was a record event on Cypress Creek. Harris County Flood Control's final immediate flood report says record flooding occurred along Cypress Creek and many of its tributaries, and that in places along the middle and lower creek, Harvey topped the April 2016 Tax Day flood. The same report lists watershed estimates of about 8,750 flooded houses in the Cypress Creek watershed and about 700 in the Little Cypress Creek watershed. During that storm, HCFCD estimated 45,000 to 65,000 acre-feet of Cypress Creek water overflowed into the Addicks Reservoir watershed. The overflow into White Oak Bayou lasted about 24 hours, a reminder that water in this part of Harris County does not always stay in the channel you see from your street (HCFCD Harvey report; HCFCD, Cypress Creek). Those are watershed figures, not a count for every Cypress street, so they don't tell you what happened on your lot.
Statewide, TDI notes that more than half of the homes flooded by Harvey were outside designated flood zones (TDI). A mapped Zone X is not a guarantee you'll stay dry. If the map is unclear, send us the address and we'll walk through flood options next to the home quote.
Little Cypress Creek is a separate watershed in the same HCFCD report, with its own estimate of 700 flooded homes in Harvey. Some Cypress-area lots drain toward that tributary rather than the main Cypress Creek channel. That is another reason we will not speak for a whole subdivision. Bridgeland flood questions, like any other Cypress address, have to be checked on the lot. Autocomplete will suggest "Bridgeland flood zone," but the answer is still the map for your parcel, not a community-wide yes or no.
Flood is left out of a regular homeowners policy. We quote both federal NFIP flood insurance and private flood. Private flood can sometimes cost less or cover more, so we compare both. More detail is on our flood insurance page.
| NFIP flood policy | Private flood policy | |
|---|---|---|
| Who provides it | The National Flood Insurance Program, run by FEMA | Private insurance companies |
| Building coverage | Up to $250,000 | Varies by company |
| Contents (belongings) | Up to $100,000 | Varies by company |
| Waiting period | Usually 30 days. There are a few exceptions, including no wait when you buy it while making, increasing, extending, or renewing a mortgage. | Varies by company |
| Temporary housing / additional living expenses | Not covered | Varies by company; ask |
| Price | Based on your location, how the home is built and the coverage you buy | Varies by company; we can help you compare it with an NFIP quote for your address. |
NFIP limits and the waiting-period rule are from FloodSmart. Private terms vary.
Hailstorms and leftover tropical wind reach the Cypress area even though the community sits well inland of the Gulf. Those losses are usually handled on the homeowners policy, not a separate windstorm policy (see TWIA). Many Texas policies set the wind and hail deductible as a percentage of the dwelling limit — that is the rebuild figure — not of the purchase price and not of the premium (OPIC).
| Dwelling limit | 1% | 2% | 3% | 5% |
|---|---|---|---|---|
| $350,000 | $3,500 | $7,000 | $10,500 | $17,500 |
| $400,000 | $4,000 | $8,000 | $12,000 | $20,000 |
| $600,000 | $6,000 | $12,000 | $18,000 | $30,000 |
Each figure is the wind/hail deductible in dollars (that percentage of the dwelling limit).
In 77433 you will see a lot of newer roofs; in parts of 77429 the shingles can be much older, so this comes up often on Cypress quotes. Companies do not all treat an aging roof the same way. Some will still write the house but settle a roof claim at actual cash value, meaning depreciation comes out first, instead of paying replacement cost. On an older roof that gap can be big. In TDI's example of a 10-year-old roof, you'd pay $5,000 yourself instead of $2,000 (TDI). If the roof is in poor condition, the company may not cover it at all, and the company should tell you when your coverage changes (TDI). A company can't decline or nonrenew a policy because of the roof's age alone, but it can because of the roof's condition (TDI, Sept. 29, 2026). If you replace the roof, tell the company so it can update the roof year.
| TDI example: 10-year-old roof | Replacement cost | Actual cash value |
|---|---|---|
| Cost of a new roof today | $10,000 | $10,000 |
| Value the policy pays on | $10,000 | About $7,000 (after depreciation) |
| Deductible | $2,000 | $2,000 |
| Insurance company pays | $8,000 | $5,000 |
| You pay | $2,000 | $5,000 |
Example adapted from TDI's home insurance guide. Your roof, depreciation and deductible will differ.
No. TWIA's Harris County area is limited to land east of State Highway 146 and inside the city limits of Seabrook, La Porte, Shoreacres, Pasadena and Morgan's Point (TWIA; TDI, Harris County windstorm map). Cypress sits northwest of Houston, well outside that line, so you don't need a separate TWIA policy. Wind and hail are normally written into the homeowners policy.
When you're ready for a Cypress quote, the most useful things to have are the street address, your current declarations page if you already have a policy, the year the roof was last replaced if you know it, and any flood-zone or elevation information you've already pulled from FEMA or Harris County. None of that is required to start, but it helps us compare companies on the same facts the same day.
Cypress houses on a slab, especially older ones in 77429, often raise the same three questions: a sudden pipe break, a leak that ran for weeks, and whether foundation movement is included. A supply line that bursts is often covered in Texas. A slow leak that went unnoticed usually is not. Mold cleanup is not covered, except to repair damage from a covered risk (TDI). TDI also flags foundation or slab damage and sewer backup as items you may have to add. The table below is a checklist for reading a Cypress policy, not the policy itself:
| Risk | In a standard Texas home policy? | What to add |
|---|---|---|
| Flood (rising water) | No; most home policies don't cover flood | A separate NFIP or private flood policy |
| Foundation or slab damage | May not be included; check your policy | Foundation/slab endorsement |
| Sewer or drain backup | May not be included; check your policy | Sewer/drain backup endorsement |
| Mold removal | Not covered, except to repair damage from a covered risk | Mold endorsement |
| Earthquakes or earth movement | Most policies don't cover it | Earthquake endorsement; ask whether it covers other earth movement. |
| Continuous water leak | Not covered | — |
| Extra costs to meet building codes | May not be included; check your policy | Building code (ordinance or law) endorsement |
We can shop home insurance for a Cypress address. If you're about to close in Bridgeland, Towne Lake or another Cypress neighborhood, give us the lot address and the date. We can get the homeowners quote moving, and your lender is going to ask for proof of coverage before you sign. It's smart to talk about flood in that same conversation. FloodSmart allows flood coverage to begin at closing — with no 30-day wait — when you buy it while making, increasing, extending or renewing a loan.
If you already have a Cypress flood quote from another source, bring it. We can help you compare it with the homeowners policy so you're not looking at the two coverages in isolation. The same is true of a lender's insurance requirement on a Bridgeland or Towne Lake closing: send the requirement letter with the address and we'll tell you what we can bind, and what still has to be a separate flood policy, before you are under a deadline.
If your address needs extra checks (an older roof, a past claim, or a flood question), we'll tell you what's still needed.
Putting up a custom house in Cypress? Ask us about builder's risk, which is meant for a dwelling that's still being built. Once you move in, you'll want a homeowners policy; the builder's warranty does not take its place.
A Cypress renewal can climb even if you never called in a claim. TDI lists rebuild cost, the age and condition of the house, roof terms, construction type, location and your deductible among the things companies use to set the price. We'll shop it when the notice arrives. Forward the renewal or the declarations page and we'll run quotes the same day.
TDI also says home insurers can't charge you more for claims from natural causes, including weather (TDI). Your premium can still change when the company files a new rate with TDI (TDI).
Yes, you can change companies mid-term. Bind the new policy first so coverage never drops, then cancel the old one, and loop in your mortgage company if premiums are escrowed. Texas rules say the old company must refund any unearned premium within 15 business days of receiving the cancellation notice or the cancellation date, whichever is later (TDI).
| What TDI says companies weigh | What to check or ask at renewal |
|---|---|
| Replacement cost: higher replacement costs mean higher premiums | Is the dwelling limit on your declarations page right for today's rebuild cost, not too high or too low? |
| Age and condition of the home | Is the roof year correct? If you replace the roof, tell your company so it can update the age (TDI). |
| Roof coverage: as roofs age, some companies switch to actual cash value | Did roof coverage change from replacement cost to actual cash value? |
| Construction materials: premiums are higher for houses built completely of wood. They're lower for houses built of brick or stone. | Is the construction type listed correctly? |
| Where you live (storms, crime) and local fire protection | Ask how your area's storm and fire-protection ratings affect the price. |
| Wind/hail deductible | What is the wind/hail deductible in dollars, and would a different one change the price? |
| Claims history (CLUE, seven years) | Any claims listed? TDI says home insurers can't charge you more for claims from natural causes, including weather. Your premium can still change when the company files a new rate with TDI (TDI). |
The price is set by the house sitting on that lot. A newer Bridgeland property and an older 77429 house can quote far apart because rebuild cost, roof condition, the wind and hail deductible, and claims history are what companies actually rate. Share the address and we'll compare real options the same day.
Only the map for your parcel can answer that. "Cypress," 77429 and 77433 are too broad. Pull your address up on the FEMA Flood Map Service Center or Harris County's Flood Education Mapping Tool.
Lenders usually don't require it outside a high-risk zone, but the local flood history is a reason to still consider it. Harris County Flood Control estimated 8,750 homes flooded in the Cypress Creek watershed during Harvey. TDI also points out that more than half of Harvey-flooded homes in Texas were outside designated flood zones. We quote both federal NFIP and private flood, and private flood can sometimes cost less or cover more, so we compare both. See our flood insurance page.
No. Rising water from Cypress Creek, Little Cypress Creek or a flooded street is still flood, and a homeowners policy leaves that out. You'd buy an NFIP or private flood policy for that risk.
There isn't one company that's best for every Cypress house. A Bridgeland address and an older home off Grant Road can land with different companies. We compare 25+ insurance companies — among them Allstate, The Hartford, Progressive, Liberty Mutual, Travelers, and Foremost — and go over the differences with you. A cheap premium can hide a large hail deductible or a roof paid at actual cash value, so we read those terms before you buy.
No. TWIA's slice of Harris County is a handful of cities east of Highway 146. Cypress is not in that slice, so wind and hail almost always sit on the homeowners policy rather than on a stand-alone windstorm policy.
Take 2% of the dwelling limit, not 2% of the purchase price and not 2% of the premium. If the dwelling limit is $400,000, a 2% wind and hail deductible means $8,000 you'd pay on a covered hail or wind claim. The table above has the other limits we listed.
Don't count on it. TDI treats foundation and slab damage, and often sewer backup, as extras you may need to add rather than automatic coverage.
A quiet claims year doesn't freeze the premium. Rebuild costs may have been updated, the roof is a year older, or the company filed a new rate with TDI. Credit can play a role too. Forward the notice and we'll shop it the same day.
Give us the lot address and the closing date and we can quote a Bridgeland or Towne Lake house. The lender will ask for proof of insurance. Mention flood when the loan is being made, because FloodSmart lets that coverage start at closing in that situation. If the house is still being framed, ask us about builder's risk.
The ZIP is just how the mail is sorted. Underwriters rate the street address: rebuild cost, roof, the flood zone on that lot, and claims. Send the street and we'll quote the house.
If a Cypress renewal just arrived, or you're heading toward a closing, we can start comparing 25+ insurance companies as soon as we have the declarations page or the street address, usually the same day. Prefer a phone call first? (713) 943-9985.
We also quote auto, life, renters and rental property insurance for people who already have a Cypress home policy with us, or who want those lines quoted together. A Cypress landlord policy is a different product from a regular homeowners policy; if you rent the house out, tell us so we quote the right form. Start with the quote form and note what else to include, or see our pages for auto, life, renters, rental property, and coverage for medical offices and strip-center owners (lessor's risk). Nearby city pages include Tomball, Katy, Houston, Sugar Land, Missouri City, Richmond and Fulshear.
Updated November 2026. Coverage descriptions are general. Prices, eligibility and terms depend on the insurer and policy.
